What it means for your money
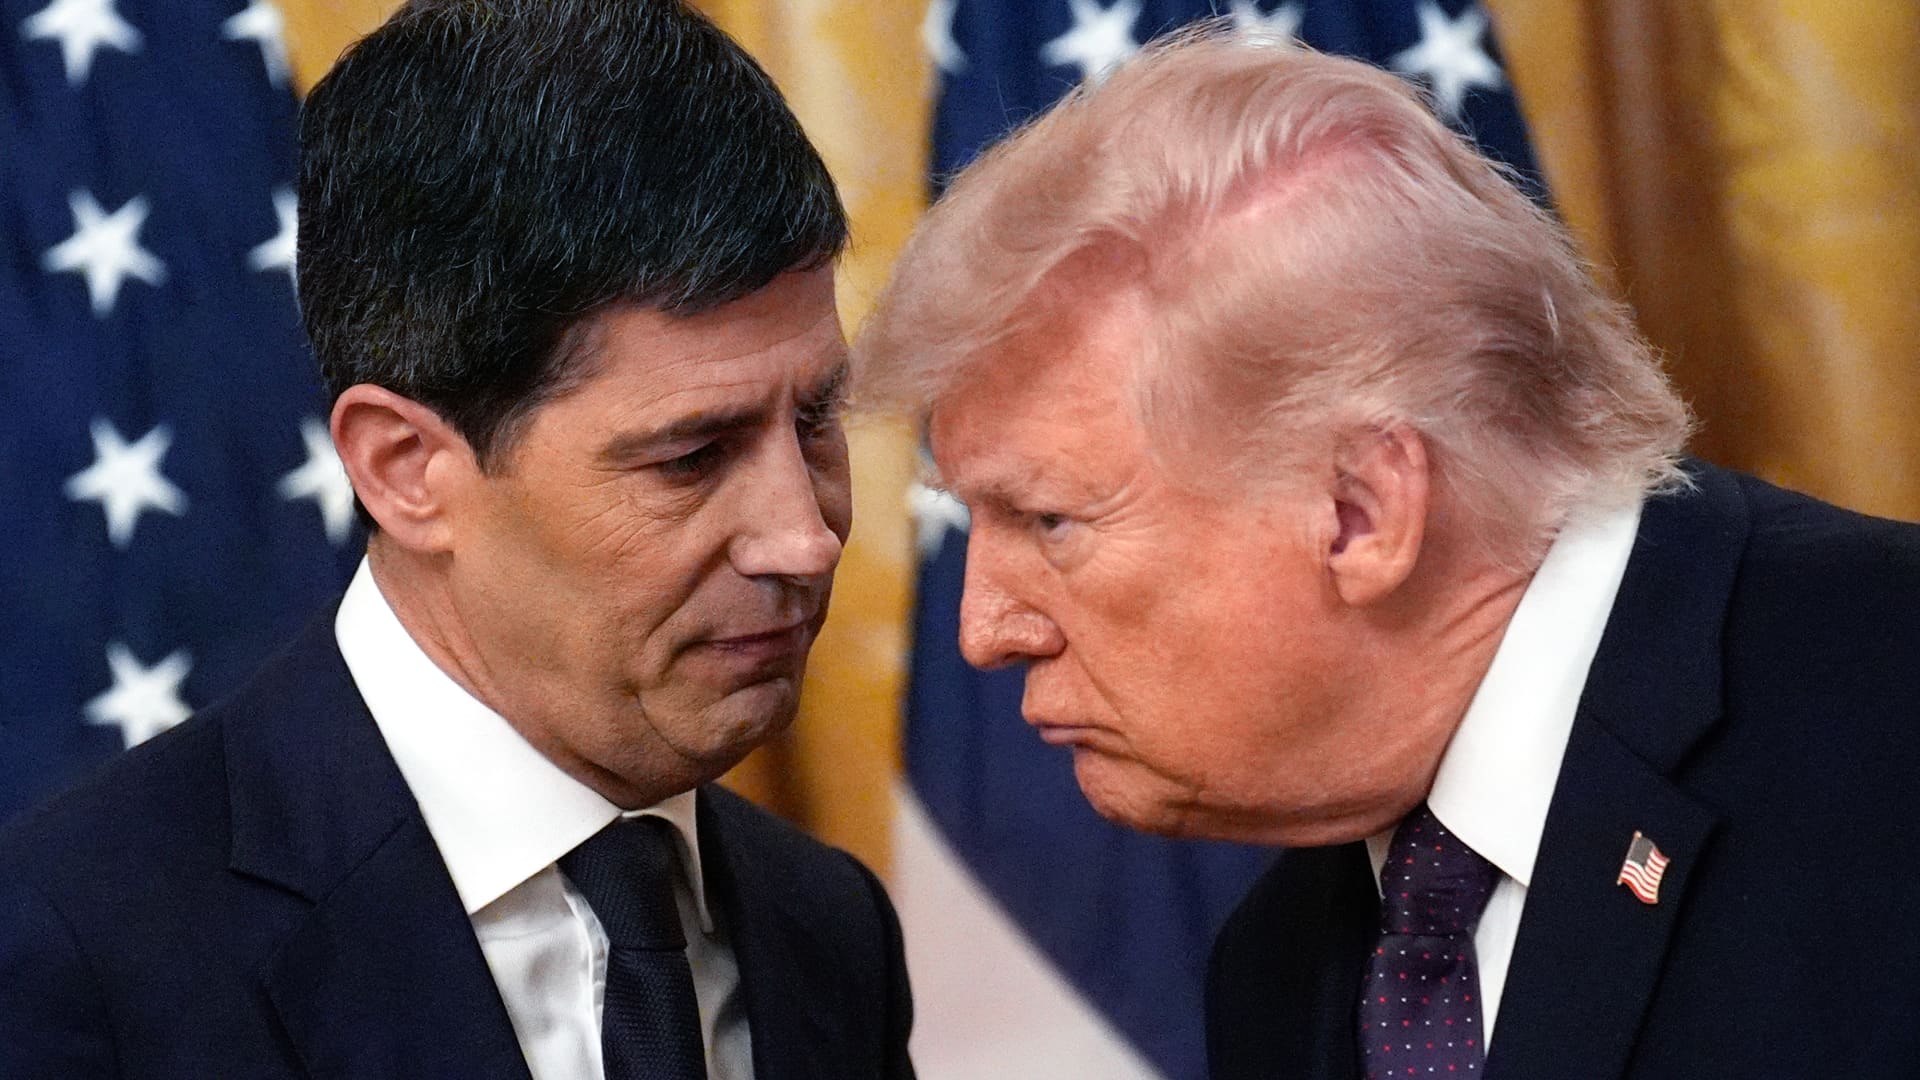
President Donald Trump and Kevin Warsh, chairman of the Federal Reserve, during a swearing-in ceremony in the East Room of the White House in Washington, May 22, 2026.
Yuri Gripas | Bloomberg | Getty Images
Market-watchers expect the Federal Reserve to raise the target federal funds rate by one-quarter of a percentage point on Wednesday amid rising energy prices and prolonged tensions with Iran. For consumers, the move could increase borrowing costs at a time when U.S. households are already under financial strain.
The consumer price index — a broad measure of inflation — continued to climb last month, bringing the annual inflation rate to 3.4% in August. Higher oil and gas prices were a significant factor, the government data showed.
Fed Chairman Kevin Warsh has expressed a commitment to bringing inflation down to the Fed’s 2% target. If the Fed raises rates to tame inflation, it would mark the central bank’s first hike in more than three years. But the move could also set up a conflict with President Donald Trump, who has pushed to lower the federal funds rate.
The federal funds rate, which the central bank sets, is the interest rate at which banks borrow and lend to one another overnight. Although consumers do not pay that rate directly, changes to the federal funds rate ripple through the economy, affecting many borrowing and savings rates.
When the Fed raises its benchmark rate, borrowing becomes more expensive for consumers and businesses, which can cool the economy and, in turn, inflation. Consumers face higher costs for mortgages, car loans and credit card debt, among other financial products. On the flip side, higher interest rates also mean savers may earn more money on their deposits.
Credit card APRs could reach record highs
Generally, shorter-term rates on consumer debt are closely pegged to the prime rate, which is typically 3 percentage points above the fed funds rate. Longer-term rates are more dependent on inflation expectations and other economic factors.
For example, most credit cards have a variable rate, so there’s a direct connection to the Fed’s benchmark. As the federal funds rate rises, the prime rate does, as well, and credit card rates follow suit within one or two billing cycles.
“Credit card rates, which are above 20%, will rise once the Fed moves to raise rates, likely to record highs,” said Mark Zandi, chief economist at Moody’s.
A young couple speaking to a car salesman.
Getty Images
Auto loans are fixed once disbursed, but a Fed rate hike could push up rates on new loans at a time when car buyers are already struggling to keep up with large monthly loan payments.
The average APR on a 48-month new car loan is expected to rise by around 12 basis points in the months following a 25-basis-point Fed rate hike, according to a recent analysis by personal finance site WalletHub.
Although federal student loan rates are fixed for the life of the loan, rates are already higher for new borrowers in the year ahead based on the last 10-year Treasury note auction in May.
Private student loans tend to have a variable rate tied to the Libor, prime or Treasury bill rates, so as the Fed raises rates, those borrowers will also pay more in interest. How much more, however, depends on the benchmark.
Fed hike may have a mixed impact on home loans
Longer-term loans follow long-term Treasury rates.
When the yield on the 10-year Treasury note, which underpins most mortgages, topped 4.95% last week — the highest level since October 2023 — the average interest rate on the 30-year fixed mortgage surpassed 7% for the first time in over a year.
“A Fed hike would not automatically mean higher 30-year mortgage rates,” said LoanDepot’s chief investment officer and head economist Jeff DerGurahian. “If the market prices in the move ahead of time and the Fed presents it as a measured step to bring inflation back to 2%, investors could view it as positive for longer-term bonds.”
“If that message lands, longer-term Treasury yields could hold steady or move lower, allowing 30-year mortgage rates to do the same. It’s essentially the Fed tapping the brakes now to keep inflation from gaining speed later,” DerGurahian said.
Other home loans feel the Fed’s actions more directly. Adjustable-rate mortgages, or ARMs, and home equity lines of credit, or HELOCs, are pegged to the prime rate. Most ARMs adjust once a year after an initial fixed-rate period. But a HELOC rate adjusts right away.
‘A potentially overlooked upside’
Deposit rates tend to correlate with changes in the target federal funds rate, which benefits savers.
“A potentially overlooked upside to elevated rates is the opportunity to capture higher yields for savings,” said Mark Hamrick, an economic analyst and founder of The Hamrick Brief.
“For both borrowing and saving, it is important to shop around for the best rates to avoid overpaying and to maximize returns,” Hamrick said.
Subscribe to CNBC on YouTube.